Thursday, June 19, 2014

Is Coke Undermanaged?!

OK, now that's a silly idea.  Coke (KO) is one of the most respected companies and known to be very well managed.   It is an excellent company for sure.

One great thing about running a blog is that I can just think out loud here and sometimes someone pulls on a thread and gets me thinking about other things (or corrects my mistakes).

After posting about a possible (or impossible) BUD/KO merger, someone commented that the operating margins can't be compared because BUD and KO operate under different models.  KO lets the bottlers do the heavy lifting and KO only makes the syrup.  This is increasingly less so due to the non-carbonated drinks they sell.  They also took over the bottling operations in the U.S.  But OK, that only accounts for 20% of global volume so it is still mostly a syrup selling operation; a very high margin and lucrative business.

But as I pointed out in the comment section, that makes the BUD/KO merger argument even stronger.  If KO has the better operating model, then how come BUD has an operating margin of 32.5% versus KO's 21.8%?    That makes no sense at all.

And as I went about my usual daily routines, I kept thinking about it and couldn't get over the fact that KO has been run so long by insiders, on how insiders tend to respect 'sacred cows' and respect tradition (in other words, it's been a tradition for 100 years to do it that way, so let's keep doing it that way).

Also, if you went up in the organization, that means you have a lot of subordinates that you helped promote over the years.  It's really hard to give a hard-working underling a department to run and then later take it away saying that we don't need it anymore.  The more likely scenario is, well, it doesn't cost us so much and we can still make our numbers so let's keep that department going.   It's probably also hard to give people nice offices over many years and then suddenly say, hey, no more offices!  We are all going to work in cubicles now.

I keep going back to that comment by the new Sony CEO that said they will never stop producing televisions because the engineers in that division are very proud of their work.  Is it any wonder what is happening there?  I've seen a lot of that when I worked in a big company too.

At KO, it's probably not so much product lines, but activities.  They probably spend a ton of money on all sorts of events with questionable returns.  I don't know (but I'm sure it will take a couple of days for 3G-type people to figure out).


It's Return on Capital, Stupid.  Not Margins!
And as I was thinking about this stuff all of the sudden I slapped my forehead and said to myself, geez, it's not the margins!  Well, margins do matter and the higher the better.  But the KO model was meant to be an asset-light model; let the bottlers build the bottling factories.  Let them do the capital intensive part and we'll just keep producing Super Bowl commercials.

So when this occurred to me, I rushed back to my desk to look at the return on capital figures for the relevant companies.

Operating Margins
So first of all, here are the operating margins for the businesses we are talking about.  Oh, and I also added Dr. Pepper Snapple Group (DPS) because they are in a similar business to KO but they are integrated, meaning they bottle their own drinks instead of relying on bottlers.   DPS is way smaller than KO so may not be a fair comp, but still, it would be an interesting benchmark.  Actually, the advantage should be to KO; size/scale benefit etc.

Here are the operating margins:

KO       21.8%
DPS     17.4%
BUD    32.5%
PEP     14.6%

So here it looks like KO is doing well against DPS and PEP.  But PEP is attached to a snack business which might have slightly different economics.  But the margin is a lot lower than BUD, who bottle and deliver their own drinks.

Return on Capital
But as I said, it may be the capital that matters, so let's look at some return on capital figures.  For capital, I will use the total of long-term debt and total equity.  I will look at operating earnings against this and call that return on capital.  Also, I won't use average equity or anything like that; I just use whatever is on the balance sheet at the end of the year.

So this is not text-book correct, but should give sort of an indication.

              Operating earnings /
              (LT debt + Total Equity)
KO*            24.2%
DPS            21.9%
BUD           14.5%
PEP            19.9%

For KO, I deducted the $10 billion or so of equity investments on the balance sheet as the equity income from those investments (bottlers) don't show up in the operating income line.  I also use total equity as minority interest is not deducted before the operating income line.

But here, the first thing you notice already is that KO's return on capital is better than DPS and PEP, but not that much better.  I thought it would have been a much bigger gap given the advantageous  business model.

And then you say, "aha!", look how awful BUD is!  But then we have to remember that BUD was created by a giant merger (and more mergers in the past) so there is a lot of goodwill on the balance sheet.

So I decided to take a look at return on tangible capital.  Here, I will only deduct goodwill, and not other intangible assets as goodwill is the pure premium paid on acquisitions, and intangibles were identifiable (but not tangible) assets that were put on the balance sheet.  I don't want to get into if the intangible valuation is fair or not.  Plus, if I deduct those intangibles, DPS capital would be negative so would destroy the elegance of my argument so let's just keep that in.

Return on Tangible Capital
So deducting goodwill from the above definition of total capital, the return on tangible capital (ROTC) becomes:

                     ROTC
KO               34.2%
DPS             58.2%
BUD            52.7%
PEP             30.2%

I was a little surprised by this result too.  KO's return on capital is good, but look at DPS and BUD.  And KO's is not much higher than PEP's ROTC given it's supposed asset-lightness.  My image is that the soda business is much more lucrative than the snack business (growth problem aside), so it was surprising to me that KO and PEP were so close here.

Greenblatt Return on Capital
And for fun, as one more layer of return on capital comparisons, I decided to use Greenblatt's Magic Formula return on capital as it does exclude all intangibles.  I will again use operating earnings on top and for the denominator I will use net current assets plus net PPE.  Let's call that NCAPPE.  

Using that I get:

                Operating earnings
                 / NCAPPE
KO              55.4%
DPS            82.9%
BUD           67.2%
PEP            42.3%

Again, this was surprising.  Both DPS and BUD beat KO on this measure.  So what happened to the asset-lightness?    Is KO pissing away the benefit of the operating model with unnecessary spending?

Here is a table that summarizes the above stuff:


Again, I deducted the equity method holdings for KO from the capital.  Net current assets was negative for BUD, so that's why it's zero there.

Conclusion
I don't think anyone can look at KO and think it's poorly managed.  And there is a question as to whether everything has to be super-optimized for super-efficient, super-returns-on-capital.

But it was interesting to go through this exercise and realize that KO is not that way out in terms of performance as I thought it was.  And again, it shows partly how incredible the 3G guys are.

If Heinz, which was considered pretty well-run (people wondered what more 3G can do after years of restructuring there) can improve so much and they can get so much value out of it, imagine what they can do at KO.  From these figures, you can see that there is a lot of room for improvement.

So while Buffett has denied Berkshire Hathaway and 3G taking KO private, that doesn't mean that Buffett doesn't want some more value extracted from KO.

And KO is so big they will need some sort of vehicle to do that with, and what better vehicle is there than BUD?

Although it is more likely that BUD acquires SABMiller, PEP and even DPS (too small?), a deal with KO would be very interesting.

Some of the pieces of the puzzle are lined up already.

  • Buffett loves what 3G is doing; he would probably love to see their work on some of Buffett's holdings 
  • KO has not been a great performer recently.  It has done well, though, but not supergreat
  • Like Ackman owning Allergan (I just threw that in there for fun; not comparing Buffett to Ackman), Buffett already owns a big stake in KO so BUD would already have some votes for a deal (and a potential supporter on the board in Howard)
  • Buffett has owned BUD in the past and probably likes the business.  We know he loves the management already, so he would gladly take all stock and maybe even buy more BUD stock or preferreds if needed to get a deal done.  Buffett would love something big to put a big chunk of capital to work. 
  • Unlike an LBO, a BUD/KO merger would have the benefits of synergies.  I know, we hate that word, but there would be a lot of synergies here, including procurement.  Someone pointed out that KO doesn't do it's own bottling, but if BUD and PEP can do a procurement deal, surely KO bottlers can do a procurement deal with BUD, so the same benefits may be realized either way. 
  • etc... 
So there are a lot of things when you think about it that makes a lot of sense here.  And yes, there are things that may be difficult.  Can you imagine the uproar of a foreign firm buying Coke?  The size of the deal alone makes it look impossible. 

But again, what's the fun if we don't dream big?! 


Tuesday, June 17, 2014

Big Dream: Anheuser-Busch InBev (BUD) / Coca-Cola (KO) Merger

This morning KO's stock price popped up on a comment by David Winters that Buffett and 3G are planning to take KO private.  He said that there are indications that something is going on, including press reports in Brazil regarding something related to 3G, KO and Buffett.

Now, I don't want to speculate on mergers and that's not what this blog is about, but it can be fun sometimes to do so.  I would usually ignore this sort of noise in the market.  Oh, and Becky Quick from CNBC called Buffett and he immediately said there's no chance 3G/BRK will take KO private.  It is way too big being bigger than the Heinz deal ($180 billion versus $23 billion for the HNZ deal).

But something has been nagging me for a while now and it was reinforced after reading the very interesting book, Dream Big: How the Brazilian Trio behind 3G Capital - Jorge Paulo Lemann, Marcel Telles and Beto Sicupira - acquired Anheuser-Busch, Burger King and Heinz.

It's really a great book that tells the story of the rise of the folks at 3G.  All business success stories are very similar but what I kept going back to is how these guys started out small and kept building things up.  They tend not to buy something to sell, but to build up.  Each acquisition turns into sort of a platform for growth and further deals. And they also give a lot of freedom to employees to take risk and grow as long as they do so prudently.  Their acquisition of BUD was seen as a long shot but it eventually happened.  It was a "big dream" that was realized.

What will they do next with BUD?  I don't think they are in it to maintain the status quo.  That's why I thought they would bid for Pepsi's snack business, for example.   I also wonder about Burger King (BKW) too.  You know 3G is in it for the long haul, so they are not going to be content sitting on it; they will make it grow and at some point down the line there will probably be some deals there too once they finish modernizing their restaurants (they already finished franchising out all the restaurants).

OK, back to BUD.

A few years ago, BUD had some agreement with Pepsi on some procurement deal so they can save costs on procurement as they share many common inputs.  Of course, this should make Pepsi too a target of a potential deal for BUD  (And in South America, beer companies also frequently sell the sodas too).

This procurement deal suggests that there would probably be some significant synergies in BUD selling sodas.  Imagine the synergies in procuring aluminum cans, and maybe even media/advertising.

And look at these figures comparing BUD and KO:

                                      BUD                    KO
Gross margin:                59%                     61%
SGA % sales:                 27%                    37%
EBIT margin:              33%                    22%

BUD's SGA includes stuff that may not technically be SGA; I just took whatever came in between gross margin and operating earnings.  In KO's case, I just took SGA as reported in the 10-K and there are other things in between SGA and operating earnings.  Also, there are probably a lot of differences in accounting standards that make a direct comparison difficult.

But in any case, this is just a quick look to see if KO might benefit from Zero-Based Budgeting (or whatever it was called).

And sure enough, as high margin and amazing KO looks, BUD is even better.

KO is very highly regarded and well-managed, but I can imagine that over the years with such a lucrative, high-margin operation, maybe there is a lot of waste that has built up over the years.  And maybe KO insiders are too generous to cut wasteful spending  (lifers sometimes have too many friends they don't want to offend).

So, maybe there could be some significant synergies between the tie-up between these two.  Getting KO operating margins up to BUD levels would increase operating earnings by 50%; that alone can pay for the premium that BUD would have to offer (presumably in a lot-of-stock / maybe-some-cash offering).

And then think of the obvious synergies of selling liquids in cans and bottles to similar retailers and other points of sale (restaurants/bars).

If what is in the above book is all true (and there is no reason to believe otherwise), this can create some huge value.

As a sanity check, here are the respective market caps and enterprise values of each:

                                             KO                BUD                       combined
Market Cap:                        $180 bn          $180 bn                  $360 bn
Enterprise Value                 $198 bn          $218 bn                  $416 bn

Yeah, that would be a huge deal.  Ridiculous, actually.  But this is a blog so I can imagine and fantasize about whatever I want!

But you know, I bet that somewhere within BUD is a spreadsheet that has all of this pro-forma-ed out on what a combined operation would look like and what synergies and costs-savings can be achieved and what the value-added would be.

Who knows, maybe it's on Brito's laptop, or maybe it's just some low-level financial analyst/intern doing it as an exercise at the suggestion of a mid-level boss.  But either way, the spreadsheet is there somewhere at BUD.  To be fair, the same one would exist for PEP, SAB Miller and every other big company that might make sense (or might not make sense).

Even a combined market cap of $360 billion (of course more if you include a takeover premium) is still way lower than the $560 billion market cap of Apple!  It's a different world.

So Buffett might have said "absolutely no chance of that" to a Berkshire Hathaway / 3G deal for KO, but he didn't say "absolutely no chance" of a BUD/KO deal, right?  And Buffett may participate too; he can buy BUD common or preferreds to help fund the deal.    So in a sense, it would still be a Buffett/3G deal, and Buffett's denial would still be true (maybe that's why he needed Quick to clarify the question to make sure that he is only denying that BRK will take KO private with 3G).

Both Buffett and Munger think Muhtar Kent is a great CEO and they seem to love him, but it's also true that Buffett really loves the guys at 3G and is impressed with what they are doing at Heinz.  HNZ too was regarded as pretty well run.  So who knows?  Maybe Buffett would really support a BUD/KO deal!

Also, BUD may have trouble doing more large beer deals due to anti-trust issues, so BUD/KO might make a lot of sense.


Wednesday, June 11, 2014

What To Do in this Market II: Gotham Funds

Many people seem to be worried that the market is a little toppy.  This is kind of strange because the market is basically flat and hasn't done anything.  But OK, the market was up 30% last year so if you include that (and the whole rally since the 2009 low) the market has come up quite a bit.

But still, smart folks like Howard Marks (who was just on CNBC yesterday) said that the market is not in bubble territory at all; maybe somewhat overvalued.   The market is still in what Buffett called the "zone of reasonableness". 

Others say the market is in nosebleed territory and is due for a correction or at least subpar returns for a long time. 

David Einhorn is short a basket of really expensive momentum stocks but he says that is only a small part of the market (mid-single-digit percentage of the market bubbled up compared to 30% of the stock market in a bubble back in 1999/2000). 

I wrote about what to do in a market that has gone up a lot and you wonder what to do.   You can see that post here: What to do in this Market.

My thoughts haven't really changed at all.  I also wrote a series of posts on market timing (even including 'pricing' the market instead of 'timing' it).  You can see my posts about Buffett the market timer here. 

In order for people to have earned 10%/year in the last 100 years, you had to own it through the depression, through war and peace, when p/e's were 7x and when p/e's were 30x.  The point is that most people would not have been successful getting in and out of the market and doing better than 10%/year, even if you used market valuation levels (instead of economic forecasts).  10% returns were not earned by being fully invested at 7x p/e, 50% invested at 15x p/e and 0% invested at 25x p/e or anything like that. 

Another way to illustrate this is if you look at something like Berkshire Hathaway.  BRK has gone down 50% three times in the past (or maybe more).  Once in the early 1970's, once in 1999 and then again during the recent crisis.  Of all the investors who owned BRK in 1970, how many have done better than the 20% or so return of the stock over the years by getting in and out of it in order to avoid the 50% drawdowns?  There may be some who were able to improve on that buy and hold.  But I doubt that there are too many people, even if they used very good valuation methods to time the sales and repurchases.

So that's sort of the way to look at the market.  As long as you have faith in the U.S. and the system at work here, you can look at the stock market in the same way.  Most people who sound clever now telling us what the market is worth and getting in and out accordingly is probably not going to outperform the market over time.   They will look good temporarily when the market goes down, though. 

OK.  So we all get that. 

Having said all of that, it is still interesting to look at what's out there in terms of alternatives for people who don't like stock market exposure.  I am really skeptical about those market-timing funds that change asset allocation according to market valuation, economic forecasts and things like that.  A lot of that stuff is great for asset gatherers and marketing; everyone hates volatility and a lot of presentations by these tactical allocators just make a whole lot of sense.  The problem is that I don't think that they perform all that well over time.

So here's the punch line: 

Gotham Funds
As you know, I am a big fan of Joel Greenblatt, and this is the latest iteration of his fund operation.  Initially, he had Formula Investing funds but shut those down and started these new funds.  Why?  Why is he running a long / short fund when he said about shorting that it is really difficult and that guys that do this are like the baseball outfielders that go, "I got it, I got it..." and then inevitably at some point go, "I don't got it..."?

He also said that buying the Magic Formula stocks and shorting the most expensive stocks on the list would have led to much more volatility on the overall portfolio than just being long because you can get really killed on the short positions. 

But here we are with Greenblatt running long/short funds. 

I'll get to that in a second, but first let's take a look at the cool website and his returns so far. 

Here's the website:  

There are some nice links there of Greenblatt's interviews on Bloomberg and CNBC.  Also, his interview in Value Investor Insight is posted there too and it's a great read.  Read that here. 

The Funds
And these are the funds that they offer: 


I know, I know.  This looks suspiciously like the long/short funds that was popular with the big mutual fund companies not too long ago.  I think most of those haven't done too well over the years.  The problem, I think, with the long/short funds that the mutual fund giants put out was that they were usually run by long only managers who suddenly had to start shorting stocks and they had no idea how to do that. 

They would buy a nice value stock and then short an expensive mo-mo stock.  It makes sense on paper, but then the value stock goes up 15% for a nice return and then the mo-mo stock goes up 50%. Oops.   

So running a long/short portfolio requires different skills than running a long only equity portfolio.  I've actually seen this happen (a long only manager transitioned to a long/short manager) with predictable results (even though this manager turned it around eventually; it helped to have been part of a legendary hedge fund firm). 

Plus, if you are working for one of the big mutual fund firms and can actually do long/short well, you would either get hired at a hedge fund or start your own.  Why would you not go out and earn your own 2 and 20? 

Performance
The funds are too new to really evaluate them, but here are the figures anyway: 


The S&P 500 total return isn't listed with these figures, so here are the year-to-date and one year returns of these funds versus the S&P 500 index  (the figures below are as of June 10, 2014):
                                                            YTD                           1 Year                        
Gotham Enhanced Return                  +10.5%                      +34.4%
Gotham Absolute Return                    +6.4%                        +21.5%
Gotham Neutral                                  +7.4%                          n.a.
S&P 500 Index                                  +5.5%                       +18.7%

So it looks like even the Neutral fund is outperforming the S&P 500 index year-to-date.  Of course, the time period is way too short for this to be relevant.

But, you know, I have been a big fan of this approach (Magic Formula) and I have a lot of confidence in Greenblatt so I would have no problem recommending any of these funds to anyone interested in this sort of thing.  I don't own any mutual funds but if I had to pick funds to invest in, I would definitely consider one of these. 

I usually don't like these long/short type funds unless they are run by people with a proven track record of doing well with the strategy.  

And I am also very skeptical of quantitative/mechanical investment methods.  Yes, value has been proven over and over to work in study after study. But when things get mechanical, I start to worry and have never been a big fan of investing mechanically  (I actually don't know how purely mechanical these funds are because there does seem to be some room for input from the managers).

But Greenblatt is different.  He came up with something after years of experience in the markets.  Usually, it's the other way around:  Some folks in academia or research departments at wire houses come up with some sort of screening method to try to create baskets that outperform.  I've seen tons of these things over the years but never saw anything that was as simple and consistent as Greenblatt's Magic Formula. 

And whatever they do here in these newer funds is an improvement on that (partly going long/short, and then an added layer of weighting the portfolio according to how cheap or expensive something is instead of equal-weighting it). 

The Evolution of Joel Greenblatt
So, let's get back to the question:  After dismissing shorting as too difficult and saying people eventually get killed doing it, why is he now running a long/short fund!? 

In order to understand this, we must go back and look at how Greenblatt has evolved over the past decade or so.

Stock Market Genius
After a nice long run as a hedge fund manager and putting up some impressive figures, Greenblatt wrote You Can Be a Stock Market Genius.  He said that he initially wrote this for individual investors.  After it was published, he realized that much of the material was over the head of most individual investors.  It turns out that this book was used successfully by many young hedge fund managers.  So he said, hmmm...    How can I reach the less experienced, more typical individual investor? 

Magic Formula
Then a few years later he wrote The Little Book That Beats the Market.   This was meant to explain how value investing works, and he even gave readers a formula to calculate return on capital and earnings yield.  He even set up a website to list the cheapest stocks according to this methodology.

Formula Funds
And then he realized that even with all of that stuff provided to the public, people still didn't act correctly and ended up not doing too well.  I think he had a record of people using the formula but human intervention prevented some from actually doing well (I forget the details, but it was something like not wanting to buy the crappy (cheap) stocks on the list, or getting scared out of the market during declines). 

So he set something up where someone will do all the work for them. 

I don't really know what went on between the Formula Funds and Gotham Funds, but my guess is that it went something like this: 

Greenblatt realized that even if Formula Funds did all the work, people will still get scared out of the market at the worst time.   I'm sure he had some experience with that and studies show that individuals tend to do way worse than the funds they own as they put money in at the highs and run away at the lows.  Some research even showed that investors collectively actually lost money in a fund that performed well.

This reminds me of the person (I mentioned this on the blog before) who told me that he has never made money, ever, in the stock market and he has been investing in the stock market during the period the Dow went from 4,000 to 12,000 (or something like that).  How can you be an "investor", have the stock market triple, and not make money?!  I think this is very typical. 

Big Secret
And at some point he wrote The Big Secret for the Small Investor.   This book was about value-weighting the indices.  Market capitalization-weighted indices didn't make sense for value investors because you were forced to own the larger cap names regardless of their valuation level.  Someone improved on this by removing the big-cap bias by equal-weighting the index.  The Big Secret is to take it a step further; the value-weighted index would give a higher weighting to the cheaper stocks and less to the more expensive ones.  This makes a whole lot of sense and I was sort of looking forward to some development in this area. 

I wrote about that here, but it seems to have gone nowhere (the website data only goes through 2010). 

But hold this thought for a second, the idea of putting more into cheaper names (instead of equal-weighting it like the Magic Formula). 

Gotham Funds
So now we get to Gotham Funds.  He once said that shorting is very difficult and that trying to long/short the Magic Formula would create more volatility, not less.  But I guess he revisited the idea after realizing that even if a method worked well, most people won't benefit from it because they can't sit tight long enough to make any money. 

So he must have been working on figuring out a way to get the long/short to work.  Plus the Magic Formula was so incredibly consistent that it must work, somehow.    By consistent, I mean that the 1st decile stocks through the 10th decile stocks performed exactly as expected over time according to their relative cheapness.  This sort of vertical consistency was strongly indicative that some sort of long/short strategy must work.  

By using a larger number of stocks and weighting the components by how cheap/expensive they are, he figured the volatility of the portfolio will be more stable (than say, buying a basket of 20 cheapest stocks and shorting the 20 most expensive ones). 

With the various options above, an investor can choose how much market exposure he wants.  Someone who is comfortable with the stock market can just buy the Enhanced Return fund, and others who don't like stock market volatility can go with the Neutral Fund. 

He did say in an interview that he wouldn't use these funds as market timing devices because most people won't be able to do that well. 

I can see the temptation to roll into the Neutral or Absolute Return funds when things look expensive and then get into the Enhanced Return when the market goes into a bear market (and gets cheap).  I imagine the fund flows would actually be the opposite of that, though.   

There is a fee for redeeming early so there will be a cost to doing that.  

And I wouldn't really advocate that at all. 

But this would still be far better than switching in and out of the stock market versus cash and bonds.  If you have to time and switch, it would be far better to do so between funds that would probably do well either way.

Plus I would guess that that would be far better than owning a fund that tries to outperform over time by switching between stocks, bonds, cash, commodity proxies and whatever else based on economic forecasts, market valuations and things like that.  Again, good luck with that. 

Why Kill Formula Funds? 
So why did he have to get rid of the Formula Funds?  I don't know.  My guess is that he thinks he found a better way so why bother keeping the old funds if these new ones are better?  He doesn't want to build a mutual fund giant by offering many variations of funds.  Most mutual fund companies love putting out new funds and using every new fad to increase AUM.  That works great for them; more funds, more work for their employees (young apprentices can gain experience by trying to run a new fund etc...).

But that's not what Greenblatt is trying to do.  He is trying to help the average individual investor make money in the market, and as long as he finds better ways to do that, he will replace the old strategies with the better ones.  If you invent and start selling refrigerators, maybe you can just stop selling ice.

But this is just my guess.  Plus,  the cost of running multiple funds is probably a big factor too.  He probably wants to keep this a small, simple operation and invest resources into research and improving the product and not wasting money increasing administrative overhead by running a bunch of different funds.

Has Greenblatt Really Evolved? 
One question is, has Greenblatt changed his views on investing after all these years?  He said in the Value Investor Insight interview that he hasn't changed. In fact, if he started all over again he would do exactly what he did the first time;  run a highly focused fund of special situations.  He said that this approach is highly volatile and he was OK with that.  In the early years when he made high returns (40-50%/year), every two or three years he would have a 20%-30% drawdown that happened pretty quickly.  But he didn't mind that. 

These recent ideas are his ideas that he thinks will work better for most people.

So this evolution is more of Greenblatt's evolution in trying to help the average investor make money in the stock market.  He wrote a book.  That didn't work.  He wrote another book. That didn't work.  He did the research for them. That didn't work.  He set up a fund for them.  That may or may not have worked, but he found a better way to make the average individual investor stick to the strategy and not get scared away. 

Bifurcated Market
By the way, here again is the performance figures for the Superinvestors of Graham and Doddsville from 1966 through 1982, a period when the stock market went nowhere.  The market was overvalued back in the late 1960's and the Nifty Fifty peak was in 1972.

But these Superinvestors did well overall through the period.   I use this table to remind myself (and others) that the overall stock market level is not always the most important thing in long term performance.

The other point, looking at this table now, that I realize is that during this time the market was probably highly bifurcated.  The mo-mo stocks were expensive back in the late 1960's, and then having been fooled by the conglomerates boom and tech stocks (-onics was the .com of the time; end your company name with these and the stock price went to the moon), investors rushed into the nifty-fifty one decision stocks (they were high quality blue chips, not fad stocks.  What can go wrong, right?).   My guess is that these Superinvestors did well during this period because they stayed away from the bubbled up areas.


I think we may be in a similar period now.  I don't really see the overvaluation that people keep talking about; I don't see excessive margins in the companies I am interested in and I don't see high p/e ratios there either.

But there are pockets of silliness here and there.  If you look at TSLA, AMZN, NFLX not to mention FB, TWTR, things look a little bubbly.  As Einhorn said, this area is not as big a part of the market as internet/tech bubble back in 1999/2000.   The collapse of some of these names may or may not take down the whole market, but either way, it's not such a big part of the stock market.

This is one reason why I am not a big fan of looking at the stock market valuation as a whole in making investment decisions.  The Superinvestors wouldn't have done so well if they sat out the market in 1966, 1972 etc...   And there was plenty do to even in 1999/2000 despite the market trading at 30x p/e (or whatever it was).

So why is this relevant to this post?

A highly bifurcated market is a great time to be long the market (if you own the right stocks) but can also be really interesting for a long/short strategy.  But of course, only if the person running it is competent.  I don't think just any long/short fund will do well;  I think most will do horribly; they will get killed on both sides (the shorts will go up and the longs will underperform!).  But if I'm right, Gotham Funds may do well on both sides; at least relatively.


Conclusion
So although nothing has changed as far as I'm concerned (with respect to what to do in the markets) I like to follow Greenblatt and I think he is the real deal. 

I am usually not a fan of long/short mutual funds (or even hedge funds unless run by someone with a good track record; never buy these things offered by the large mutual fund companies!), and I am not really a big fan of mechanical investing either. 

But again, Greenblatt is a veteran that has a proven track record in the markets so he is not just some academic coming up with a nice theory trying to sell you something.  So I wouldn't have much reservation about these funds based on it being a long/short strategy and quant-based. 

Also, I know that the Magic Formula has been controversial in the past; that people have not been able to duplicate Greenblatt's results.  I haven't done any work on that myself but I suspect a lot of that is going to be because of the data. 

When I worked at big firms, a lot of resources went into cleaning up the database (that were presumably already cleaned up by the vendor).  So it would be really difficult in any case to duplicate results without a good staff actually going over the raw data first.  You'd be surprised how much silliness gets into these backtests if you don't actually check the data yourself (or have someone do it for you).  This would include things like dropping stocks where the financial data is suspect or meaningless (data vendors won't do that).

So,

  • In this bifurcated market we know that there are decent stocks to buy and the Magic Formula type things will outperform over time.  No need to get out of the market even if the whole market is expensive (and some great investors say it's not) if there are reasonably priced stocks to own.  And the Magic Formula is not a bad way to be long (assuming the Gotham Funds use a similar methodology). 
  • On top of that, the returns in these funds will be enhanced by the weighting strategy of buying more of things that are cheaper instead of equal weighting them (read the The Big Secret for the Small Investor and go to the website (valueweightedindex.com) to see how that works).
  • And then you have a short portfolio overlay on top of this using the same strategy in reverse; shorting more of the more expensive things.  The short book is risk managed by having smaller positions per name so as not to get killed by the occasional NFLX / AMZNs.  
  • People will always be afraid of some stocks due to recent bad news (and therefore underprice them) and will always adore others (and therefore overprice them).  As long as this continues to be the case, the strategy should work.  
It's such a simple idea and it sounds too good to be true. And yes, the mutual fund industry is littered with funds that tried similar things in the past.  

I will tell you, though, that this is different than those past attempts by a wide margin; mostly due to the experience of Joel Greenblatt, the research that he has done and disclosed to demonstrate that the ideas actually work etc...  

The $250,000 minimum investment might be a high hurdle for some younger individual investors, but if I wasn't actively managing my own account, I would certainly consider putting a decent chunk of my risk capital into these funds. 

Anyway, I don't recommend mutual funds here all that often, but take a look! 

Thursday, May 1, 2014

ARES: Ares Management, L.P.

As we all hold our breath for the Alibaba IPO filing (OK, or maybe not.  I am actually looking forward to it even though I have no intention of buying any shares), here's a look at another S-1 filed by Ares Management (ARES) recently.  (As I was finishing this up, it turns out that the deal was priced at $19/unit tonight).

Alleghany
This IPO is on topic here because I do like to look at and talk about alternative asset managers, but also because Alleghany (Y) took a 6.25% stake in ARES last year.  With interest rates so low, they were looking for some expertise in the area of fixed income to earn some higher yield.  Markel (MKL) too, has recently added some expertise in this area (assigned a full time fixed income manager).

They paid $250 million for their stake, and they own 12.5 million shares (I will ignore the difference between Operating Group Units and Common Units as they are exchangeable 1-1) so that comes to $20/share.    ARES was just priced at $19/unit, so the public gets a chance to get into ARES for less than what Y paid for it.

By the way, what valuation did Y pay for ARES?   6.25% stake at $250 million gives a total value of ARES of $4 billion.  In 2012, economic net income was $402 million, so that comes to 10x the economic income for the most recent full year (as of July 2013).  But in 2013, economic net income fell to $329 million, so $4 billion would be 12x that.

Without getting into too much detail, I think economic net income is the cleanest way to look at these alternative managers.  Net income can be messy due to the consolidation of the funds they manage and the GAAP treatment of unrealized gains etc. Distributable income is good too, but that is based on realized gains and incentive fees so can be lumpy.  Economic net income will include unrealized gains and losses (that affect incentive fees) as they occur, so reflects more the reality of what is happening in the respective periods.

Anyway, who are these guys?

Background/Co-Founder
I am not a fixed income guy so am not too familiar with ARES, but apparently they are very highly regarded and run a very good operation.  The founder is the brother-in-law of Leon Black of Apollo Global Management and was a co-founder of Apollo.  ARES is a long time ago spinoff out of Apollo (1997).  Despite the reputation of Drexel Burnham Lambert, there have been a lot of good people that have come out of there.  Richard Handler who now runs Leucadia is also a Drexel guy.  Joel Greenblatt was initially funded by Milken himself.

Here's the blurb about Ressler from the S-1:
        Antony P. Ressler.    Mr. Ressler is a Co-Founder of Ares and the Chairman and Chief Executive Officer of our general partner. He is a Senior Partner of Ares in the Private Equity Group and serves as Chairman of the Management Committee. Mr. Ressler also serves on the Board of Directors of ARCC. Prior to Ares, Mr. Ressler was a co-founder of Apollo Management, L.P. in 1990 and was a member of the original six-member management team. Mr. Ressler oversaw and led the capital markets activities of Apollo Management, L.P. and Lion Advisors, L.P. from 1990 until 1997, particularly focusing on high yield bonds, leveraged loans and other fixed income assets. Prior to 1990, Mr. Ressler served as a Senior Vice President in the High Yield Bond Department of Drexel Burnham Lambert Inc., with responsibility for the New Issue/Syndicate Desk. Mr. Ressler is also a member of the Board of Directors of Cedars-Sinai Medical Center, is Finance Chair and a member of the Executive Committee of the Los Angeles County Museum of Art (LACMA), and is Founder and Co-Chairman of the Alliance for College Ready Public Schools, a group of eighteen charter high schools and middle schools based in Los Angeles. Mr. Ressler is also one of the founding members of the board and Finance Chair of the Painted Turtle Camp, a southern California based organization (affiliated with Paul Newman's Hole in the Wall Association), which was created to serve children dealing with chronic and life threatening illnesses by creating memorable, old-fashioned camping experiences. Mr. Ressler is also a former member of the board of directors of Air Lease Corporation and WCA Waste Corporation. Mr. Ressler received his B.S.F.S. from Georgetown University's School of Foreign Service and received his M.B.A. from Columbia University's Graduate School of Business.

There are other co-founders and I don't mean to dismiss them as unimportant.  But it seems from the ownership and his Chairman/CEO status that he is the main founder:

Common Units with Voting Power Beneficially
Owned(1)(2)
Ares Operating Group Units Beneficially
Owned(1)(2)(3)
Name of Beneficial Owner
Number % Prior to
the Offering
Transactions
% After the
Offering
Transactions
Assuming the
Underwriters'
Option is Not
Exercised
% After the
Offering
Transactions
Assuming the
Underwriters'
Option is
Exercised in
Full
Number % Prior to
the Offering
Transactions
% After the
Offering
Transactions
Assuming the
Underwriters'
Option is Not
Exercised
% After the
Offering
Transactions
Assuming the
Underwriters'
Option is
Exercised in
Full
Directors and Named Executive Officers:
Michael J Arougheti
————10,445,6135.22%4.94%4.88%
David B. Kaplan
————10,445,6135.22%4.94%4.88%
John H. Kissick
————4,048,8122.02%1.92%1.89%
Antony P. Ressler
————48,890,39024.45%23.13%22.84%
Bennett Rosenthal
————10,445,6135.22%4.94%4.88%
Paul G. Joubert
————————
Michael Lynton
————————
Dr. Judy D. Olian
————————
All directors and executive officers as a group (persons)
————85,444,18942.72%40.43%39.92%


One nice thing about Ressler is that he is 53 years old.  Many of us are Buffett fans and he is not so young.  We were also fans of Leucadia, but those founders retired (or nearly retired).  Howard Marks is not so young either.   So it's kind of a good thing when we look at something and the owner-founder is young and still has a lot of runway.

Some Charts
OK, and here are some of the usual things that show up in S-1's.  AUM has been increasing rapidly at ARES, just like at other alternative managers.  I have mixed feelings about this, as usual.  It's nice to see this kind of growth, and yes, there may be more growth to come. 

But on the other hand, how many more years can alternative managers keep growing assets like this?  Equity mutual fund managers grew assets at incredible rates too in the 1990's.  And the scary thing was that all of the equity managers were growing assets at rapid rates.   Is that sustainable?     You have two problems with that:  
  1. If they all keep growing AUM at such rates, can there really be that much opportunity for the capital to be deployed?
  2. If AUM keeps growing at these rates, can they maintain the sort of high rates of return they achieved at smaller AUM levels? 
Some of these guys will tell you that it's OK because their asset growth is coming from addition of new strategies; it's not like private equity is building up tons of cash to invest (a lot of AUM growth at the private equity firms are not coming from private equity AUM; they are growing in other areas like hedge funds, fund of funds, credit, real estate etc.) 

But then we have to keep in mind that the economies of scale don't work as well when AUM is increased by adding strategies because that often entails hiring (or buying) new teams.  The money management model is attractive when you have fixed costs and then just add AUM on top of it so all the incremental fees go right to the bottom line.  This doesn't happen when you buy a hedge fund manager or fund of funds company.   

But yes, there are other benefits, (cross-marketing, one-stop shop etc.) I suppose.   Some synergies might come from one legal department, one human resource dept, shared sales and marketing force,  research etc).

Anyway, I digress. 

AUM Growth at ARES

GRAPHIC

Assets Under Management


Capital BaseFee Revenue Base


GRAPHIC


GRAPHIC


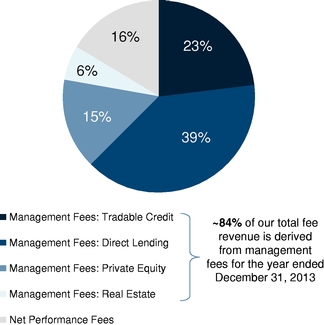
The earnings at ARES tends to be stable compared to other alternative managers as 84% of their fee revenue is management fee income.  So in that sense, economic net income seems to be a fine thing to look at (as opposed to others more heavily weighted towards private equity where incentive/performance fees tend to be large and lumpy).

Their asset base seems pretty steady too as a lot of the assets are locked up for a long time, including a lot of listed closed end fund assets.

They say:
Stable Earnings Model        We believe we have a stable earnings model based on:

•  A significant portion of the capital that we manage is long-term in nature.  As of December 31, 2013, approximately 58% of our AUM was in funds with a contractual life of seven years or more, including 15% that was in permanent capital vehicles with unlimited duration. This has enabled and continues to enable us to invest assets with a long-term focus over different points in a market cycle, which we believe is an important component in generating attractive returns.
•  A significant portion of our revenue is generated from management fees.  For the year ended December 31, 2013, approximately 84% of our total fee revenue was comprised of management fees (including 18% attributable to ARCC Part I Fees) and approximately 16% was comprised of performance fees. From 2011 to 2013, management fees averaged 81% (including an average of 18% attributable to ARCC Part I Fees) of our total fee revenue. Management fees, which are generally based on the amount of committed or invested capital in funds we manage, are more predictable and less volatile than performance fees.
•  We have a diverse capital base across funds from four distinct groups.  For the year ended December 31, 2013, approximately 40% of our total fee revenue was generated by our Direct Lending Group, which includes fees generated by over 25 funds, and approximately 33% of our total fee revenue was generated by our Tradable Credit Group, which manages approximately 75 investment funds. We have a well-balanced and diverse capital base, which we believe is the result of demonstrated expertise across each of our four investment groups.
•  A significant portion of our performance fees are linked to credit investment strategies.  Over the last three years, a significant portion of our performance fees have been generated by funds with credit investment strategies, which generally generate regular interest income. For the years ended December 31, 2013, 2012 and 2011, 55%, 41% and 40%, respectively, of our net performance fees were from contractual interest payments on debt investments and dividends received by our funds. As a result, we believe that our performance fees are more predictable and less volatile than investment managers predominantly focused on private equity-style investment strategies, in which performance fees are typically based on market gains and losses


Investment Strategies
Here are the four main areas of investing that ARES is involved in.

GRAPHIC


And here are the targeted net returns of the respective strategies: 


GRAPHIC

(1)  Target returns are shown for illustrative purposes only after the effect of any management and performance fees. No assurance can be made that targeted returns will be achieved and actual returns may differ materially. An investment in any of the mandates is subject to the execution of definitive subscription and investment documentation for the applicable funds.
(2)  An investment in our common units is not an investment in any of our funds, and the assets and revenues of our funds are not directly available to us. Further, the returns of our funds are not necessarily indicative of Ares Management, L.P.'s operating results or of the price of our common units.
(3)  Comprised of investment vehicles with and without leverage. 

And the usual thing about the growth of alternative assets as a class: 
Increasing Importance of Alternative Assets
        Over the past several years, investor groups of all types have meaningfully increased their capital allocations to alternative investment strategies. McKinsey and Co. estimates that alternative investments (which includes private equity, hedge funds and investments in real estate, infrastructure and commodities in a variety of vehicles) grew at a 14% compound annual growth rate versus non-alternative investments at 2% for the six year period from 2005 to 2011. We expect this current trend will continue as the combination of volatile returns in public equities and low-yields on traditional fixed income investments shifts investor focus to the lower correlated and absolute levels of returns offered by alternative assets.
Increasing Demand for Alternative Assets from Retail Investors
        Defined contribution pension plans and retail investors are demanding more exposure to alternative investment products to seek differentiated returns as well as to satisfy a desire for current yield due to changing demographics. According to McKinsey & Co., retail alternative investments will account for 13% of U.S. retail fund assets and 24% of revenues by 2015, up from 6% and 13% as of year-end 2010, respectively. ARCC has benefited from this growing demand, increasing its assets under management from approximately $300 million in 2004 to $9.7 billion in 2013. Our Tradable Credit and Real Estate Groups have raised three publicly traded vehicles over the past two years. With an established market presence, we believe we are well positioned to take advantage of the growing opportunity in the retail channel.

The interesting thing here is the growing demand for alternative assets from retail investors.  ARES has four listed closed-end funds so already directly runs retail money.  This is interesting because Blackstone, Oaktree and others frequently mention the growing retail demand for alternative investments.  Oaktree sub-advises mutual funds (as does Blackstone), but they don't have any direct product offering like ARES does.  Could this sort of thing be what Oaktree is looking into now?

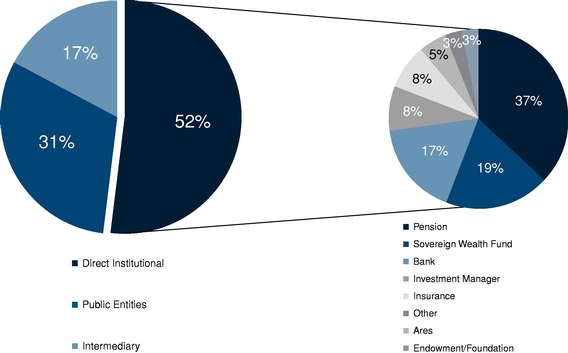
        The following charts present our AUM by channel and our retail and our direct channel by investor, in each case as of December 31, 2013.


AUM By Channel AUM By Direct Institutional Channel
Direct Channel By Investor Type

GRAPHIC


        As of December 31, 2013, 52% of our approximately $74 billion in AUM is from our direct institutional relationships. The majority of these assets are from pension funds, sovereign wealth funds, banks, investment managers and insurance firms. Our top 10 direct institutional investors account for approximately 19% of our AUM, and no such single investor accounts for more than 4% of our total AUM. Our publicly traded entities, including ARCC, ACRE, ARDC and ARMF, account for 31% of our AUM. Ares has over 350 institutional investors and over 200,000 retail investors across our four publicly traded investment vehicles.  (emphasis mine)

I will take a quick look at some of these listed closed-end funds later (maybe another post).  They do look interesting, particularly for people who are interested in fixed income investments (and I generally am not).  How often do we look at an alternative manager and are able to buy into their fund right away?

Performance
Here are some things that show the investment performance of ARES.

Tradable Credit Group:
The following table presents our Tradable Credit Group's gross annualized returns since inception and our Tradable Credit Group's relative index outperformance:
GRAPHIC


(1)  Annualized returns over the same period, net of management fees, were 5.0% for Ares U.S. Bank Loan Aggregate Composite and 8.6% for Ares U.S. High Yield Aggregate Composite.

(2)  Annualized returns over the same period, net of management fees, were 13.7% for Ares Multi-Strategy Credit Aggregate Composite and 15.8% for Dedicated Special Situations Funds.

(3)  In addition to outperforming the relevant indices on an aggregate basis since inception by the indicated amounts, each of the investment strategies has outperformed the relevant indices on an annual basis in the majority but not all calendar years since inception.

         The Tradable Credit Group manages approximately 75 funds across strategies in long-only and alternative credit. No single fund contributed 10% or more of the Tradable Credit Group's 2013 total management fees, whereas over 30 funds contributed over 1% of the group's total management fees. The Tradable Credit Group manages four of our significant funds: ECO I, an alternative credit hedge fund designed as an enhancement to existing fixed income strategies or as an alternative to global equity strategies, AELIS VI, a long-only comingled fund that opportunistically acquired a credit portfolio from a bank in 2008 and is currently in harvest mode, CSF, an alternative credit managed account with a flexible and opportunistic mandate to invest in corporate credit funds, and ASIP II, an alternative credit managed account with a flexible and opportunistic mandate to invest in corporate credit. In addition, the following table includes performance information for the fund with the greatest amount of management fees for the year ended December 31, 2013 for each of the high yield and special situations sub-strategies within the Tradable Credit Group, which are not otherwise represented by the significant funds.


    As of December 31, 2013    
      Net Returns
(%)(2)
   
Fund
 Year of
Inception
 Assets Under
Management(1)
 Since
Inception
 Past
5 Years
 Past
3 Years
 Investment Strategy  
    (Dollars in millions)         
ECO I(3)(4)
  2006 $2,632  1.9  27.4  11.0  Alternative: Multi-strategy 
HY II(3)
  2007 $369  9.0  17.2  9.0  Long-only: High yield 
AELIS VI(5)
  2008 $850  16.6  n/a  15.2  Long-only: Loans 
CSF(6)
  2008 $1,732  14.5  15.9  9.6  Alternative: Multi-strategy 
ICOF I(5)
  2008 $236  18.3  25.4  13.6  Alternative: Special situations 
ASIP II(3)
  2009 $820  11.1  n/a  7.4  Alternative: Multi-strategy 
(1)
Assets under management equals the sum of the NAV for such fund, the drawn and undrawn debt (at the fund-level including amounts subject to restrictions) and uncalled committed capital.
(2)
Net numbers are after giving effect to management fees and performance fees as applicable. ECO I, AELIS VI, CSF and ICOF I net numbers are also after giving effect to other expenses.
(3)
The net return is calculated using the modified Dietz method, which is an estimate of the time-weighted return and adjusts portfolio cash flows according to the time they were invested in the portfolio and is calculated by dividing (A) net asset value change over the period minus cash flow, by (B) (a) beginning net asset value plus (b) weighted cash flow. Net returns are annualized.
(4)
From the inception of ECO I through year-end 2008, the fund was managed primarily as a long-only strategy, employing 3-4x debt to equity leverage during a period of high volatility within the credit markets, which impacted fund performance. Beginning in 2009, ECO I's strategy was modified to incorporate a broader array of hedges and other shorting instruments with targeted leverage levels reduced to 1-1.5x on a debt to equity basis. AUM includes capital committed by CSF, a fund of funds.
(5)
The net return is an annualized net internal rate of return computed based on cash flows to and from fee-paying limited partners and the partners' ending capital for the period. The past five and three years net returns are calculated using beginning partners' capital for the period.
(6)
The net return is an annualized net internal rate of return computed based on cash flows to and from investments and the partners' ending capital for the period. The past five and three years net returns are calculated using beginning partners' capital for the period. CSF is a fund of funds and AUM represented may include AUM that has been committed to other Ares funds.  
Direct Lending Group
        Our Direct Lending Group has earned accolades such as co-winner of Senior Lender of the Year, Americas in 2013 (Private Debt Investor), 2013 Mid-Market Lender of the Year (M&A Atlas), 2013 Third Place CEO Award for Michael J Arougheti as Chief Executive Officer of ARCC in the Brokers and Asset Managers and Exchanges Category (Institutional Investor All-America Executive Team). Our European team has grown to become a market leader in the region and was named the Specialty Lender of the Year, EMEA in each of 2010, 2011 and 2012 (Real Deals) and the co-winner of the Unitranche Lender of the Year in 2013 (Private Debt Investor). The group has demonstrated a track record of aggregate outperformance, as evidenced by ARCC's performance. The following table presents total shareholder returns of ARCC since its initial public offering in 2004 against certain market indices for the same period:
GRAPHIC

(1)  In addition to outperforming the relevant indices on an aggregate basis since inception, ARCC has outperformed the relevant indices on an aggregate basis for the last five year and seven year time periods. On an annual basis, ARCC has outperformed in five of the ten year-end return periods. 


        The Direct Lending Group manages over 25 funds in the United States and Europe. While the group manages a range of funds, ARCC and ACE I, each considered a significant fund, combine for over 90% of the group's total management fees for 2013. ARCC is a publicly traded business development company that principally originates and invests in first lien senior secured loans, second lien senior secured loans and mezzanine debt in the United States. ARCC has increased its assets under management from approximately $300 million in 2004 to $9.7 billion in 2013 and is the largest of our funds both by AUM and management fee revenue. ACE I is a 2007 vintage comingled fund focused on direct lending to European middle market companies.


    As of December 31, 2013    
      Annualized Returns
(%)
   
Fund
 Year of
Inception
 Assets Under
Management(1)
 Since
Inception
 Past
5 Years
 Past
3 Years
 Investment Strategy  
    (Dollars in millions)         
ARCC(2)
  2004 $9,658  14.1  38.4  12.3  U.S. direct lending 
ACE I(3)
  2007 $780  3.1  5.4  7.2  European direct lending 
(1)
Assets under management equals the sum of the NAV for such fund, the drawn and undrawn debt (at the fund-level including amounts subject to restrictions) and uncalled committed capital but, with respect to ARCC, does not include AUM of the SSLP (through which ARCC co-invests with affiliates of General Electric Company) or Ivy Hill Asset Management, L.P. (a wholly owned portfolio company of ARCC).
(2)
The annualized return is the return to ARCC's stockholders based on ARCC's public stock price and is calculated assuming dividends are reinvested at the end of day stock price on the relevant quarterly ex-dividend dates. The return is calculated assuming stockholders did not participate in the rights issuance as of March 20, 2008.
(3)
The annualized return is an annualized net internal rate of return computed based on cash flows to and from fee-paying limited partners and the partners' ending capital for the period. The past five and three years net returns are calculated using beginning partners' capital for the period. Includes the period from inception until March 2013, during which ACE I was structured as an operating company and responsible for the costs of its employees and operations. Beginning March 2013, the net annualized return is net of management fees and expenses. Data also reflects the effect of foreign currency fluctuations. AUM includes capital committed by CSF, a fund of funds in the Tradable Credit Group. 
By the way, here's a slide from an ARCC investor presentation showing non-accruals in their portfolio over time:


ARES has a really good website and a section for their publicly listed investment vehicles.  The presentation and reports are very good.  Check it out here:  www.arespublicfunds.com

Private Equity
        Our Private Equity Group has the expertise and mandate to deploy capital in compelling situations across economic environments. This is evidenced by the investment track records of ACOF II and ACOF III, both of which are leading funds in their respective vintages despite deploying capital in vastly different economic environments. The track record of our three fully deployed funds contributed to the successful fundraise of ACOF IV, which raised $4.7 billion, a 30% increase over the predecessor fund. The following table presents gross IRRs since each of the respective funds' inception and certain other data. 
GRAPHIC


(1)  Net IRRs over the same period were 14%, 15% and 25% for ACOF I, ACOF II and ACOF III, respectively. 

        The Private Equity Group manages five comingled funds in private equity. ACOF II, ACOF III and ACOF IV, each considered a significant fund, combine for over 90% of the Private Equity Group's 2013 management fees. Each fund focuses on majority or shared-control investments, principally in under-capitalized companies. Both ACOF II and III are in harvest mode while ACOF IV is in deployment mode. In addition, performance information for ACOF Asia has been included to provide information about the China growth capital sub-strategy within the Private Equity Group.


    As of December 31, 2013    
      Net Annualized Returns
(%)(2)
   
Fund
 Year of
Inception
 Assets Under
Management(1)
 Since
Inception
 Past
5 Years
 Past
3 Years
 Investment Strategy  
    (Dollars in millions)         
ACOF II(3)
  2006 $1,179  14.6  24.4  25.6  U.S./European flexible capital 
ACOF III(3)
  2008 $3,661  24.7  25.5  17.9  U.S./European flexible capital 
ACOF Asia(4)
  2011 $229  n/a  n/a  n/a  China growth capital 
ACOF IV(4)
  2012 $4,646  n/a  n/a  n/a  U.S./European flexible capital 
(1)
Assets under management equals the sum of the NAV for such fund, the drawn and undrawn debt (at the fund-level including amounts subject to restrictions) and uncalled committed capital.
(2)
Net numbers are after giving effect to management fees, the general partner's carried interest and other expenses.
(3)
The net annualized return is the internal rate of return computed based on cash flows to and from investments and the partners' ending capital for the period. The past five and three years net return are calculated using beginning partners' capital for such period.
(4)
The net return is not shown due to the fund's recent vintage. 

Real Estate
        In 2013, PERE ranked AREA as a Top 15 real estate manager based on equity raised from January 2008 to April 2013. Additionally, Standard & Poor's ranked our primary and secondary special servicer as above average. The following table presents performance data of our primary strategies:
GRAPHIC
    (1)
    Annualized realized and unrealized returns over the period since inception net of management fees, the general partner's carried interest and other expenses were 11.0% for the U.S. Value Add strategy and 12.7% for the European Opportunistic strategy.
    (2)
    Represents the dollar weighted average of the unleveraged effective yield of ACRE's principal lending portfolio measured at the end of the seven quarterly periods since inception through December 31, 2013. Unleveraged effective yield is based on the contractual interest rate (adjusted for any deferred loan fees, costs, premium or discount) and assumes no dispositions, early prepayments or defaults and does not take into consideration the impact of leverage utilized by ACRE, fees, expenses and other costs incurred by ACRE or its stockholders, which are expected to be significant. Unleveraged effective yield does not represent net returns to investors of ACRE. 
       The Real Estate Group manages over 35 funds in real estate debt and real estate equity. Two funds, Euro RE Fund III and ACRE, contributed 10% or more of the Real Estate Group's 2013 management fees whereas over 15 funds contributed over 1%. The Real Estate Group managed one significant fund, EU III, which is a comingled private equity fund focused on real estate assets located in Europe with a focus on the UK, France and Germany. In addition, performance information for two additional funds has been included to provide additional information about the U.S. real estate private equity and real estate debt sub-strategies within the Real Estate Group.


    As of December 31, 2013    
      Annualized Returns(2)/
Effective Yield
(%)
   
Fund
 Year of
Inception
 Assets Under
Management(1)
 Since
Inception
 Past
5 Years
 Past
3 Years
 Investment
Strategy
 
    (Dollars in millions)         
EU III(3)
  2007 $1,263  5.8  8.8  9.2  Real estate equity 
U.S. VII(3)(4)
  2008 $803  14.1  14.1  19.9  Real estate equity 
ACRE(5)
  2012 $1,111  6.6  n/a  n/a  Real estate debt 


What's it Worth? 
OK, so let's just take a quick look at what this thing is worth.  Without getting into the details, let's just look at economic net income (ENI).  That's what is important here.  And next to that I'll put the average fee earning AUM figure so we can come up with a normalized earnings figure.

           Average
           fee-earning
           AUM                   ENI     
2011   $35,947               $193.9
2012   $43,901               $402.4
2013   $53,374               $328.7
(in millions)

I'll use for shares outstanding 211,363,636 which is the figure shown as "Common units outstanding after this offering assuming exchange of all outstanding Ares Operating Group Units for newly issued common units" plus 3,981,363 dilutive restricted shares for a total of 215,344,999.  Let's just call that 215 million.   There are some potential greenshoe shares and options but I'll leave that out for now.

The shares were just priced at $19/share, that's a $4.1 billion market cap.  That's 10.2x 2012 ENI (economic net income) and 12.5x 2013 ENI.

Since ENI went up and down a little in the past three years (did I say that ENI at ARES would be more stable due to high percentage of management fee versus incentive fee?) and we don't know which is a more normal year, 2012 or 2013 (or 2011), we can take an average of the three years.

But an average wouldn't quite work because we see that AUM has been steadily increasing (and not just in the past two years).  So we would have to scale the ENI by AUM.

So let's just see what the ENI percentage is versus AUM.

ENI as a percentage of average fee earning AUM
2011         0.54%
2012         0.92%
2013         0.62%
average:   0.69%

There was $59 billion in fee earning AUM at the end of 2013, so assuming that stays the same, the normalized earning power of ARES is $407 million ($59 billion x 0.69%).   That means ARES would be trading at 10.1x normalized ENI.  Another way to look at it is that ARES has a normalized ENI power per share of around $1.89/unit.

I ignored balance sheet items here as there is only $3.29/unit in tangible equity per share, and accrued incentive fees is actually lower than incentive fee (bonus) payable.  And any investment income from investments on the balance sheet is already included in ENI.

Also, since this is a partnership, this ENI figure is pretax; unit holders will have to pay taxes on whatever profits is earned (and flows through to the unit holder whether distributed or not).   Since much of the income seems to be from interest income, there will probably be very little that can be treated as long term capital gains.

Why Buy a Fixed Income Manager at the Top of a Bond Bubble? 
Of course, we have to think about this.  The bond market seems to be at an unsustainably high level.  If the bond market turns, won't guys like ARES get hurt?  Maybe.  But ARES is not PIMCO.

In fact, Alleghany bought into ARES precisely because interest rates were so low and they wanted exposure to some expertise in investing in such a period.

I sort of suspect interest rates can stay low for a lot longer than many people think (like in Japan).  If that is the case, then these guys should continue to do well.

If interest rates start to rise because of a stronger economy they should benefit too from more potential deals (same as banks).

Conclusion
Anyway, this is just a quick look at this interesting company.  It is run by very good people and is partially owned by Alleghany, a company that I respect.  The stock was priced at a level below what Alleghany paid, and it looks like it is priced at around 10x a normalized earnings figure, which is very reasonable.

This 10x multiple doesn't seem to include huge realizations/gains that a lot of other private equity/alternative managers booked last year.   Since this is mostly credit, the ENI may be more stable and not bubbled up so much.

Also, ARES funds (including ARCC, the flagship listed vehicle) seems to have done well through the crisis.  It is a credit manager and they had their own real life stress test and it looks like they got through it OK with decent performance.

Three years may not be enough to normalize earnings, but again, due to the nature of the business (mostly interest and dividend income versus huge gains on leveraged equity), this may not be too far off.

But I guess we'll know more after the first earnings conference call when we'll start to get more color on the business.